
As I build my boutique wealth management firm, I'm looking to partner with the right people and families. If you've ever wondered whether it might be a fit, or you just want a second opinion on your current setup, feel free to reach out. Always happy to talk.
Just reply to this email.
4% Rule: How much money do you actually need to retire?
One of the most common answers is the 4% rule. If you have $2.5m invested, you can spend 4% ($100k) in your first year of retirement and increase that amount with inflation every year after that. Simple enough. But, like most financial rules, it's never quite that simple.
The 4% rule came from research done by financial planner William Bengen in the 1990s. He looked at historical market returns and tried to answer a simple question: How much could someone withdraw from their portfolio every year without running out of money over a 30-year retirement?
His answer was a little over 4%.
4% wasn’t designed to be the “right” amount to spend. It was designed to survive some of the worst periods in market history, including the Great Depression and the high inflation of the 1970s.
In many historical periods, someone following the 4% rule wouldn’t have just avoided running out of money. They would have died with significantly more than they started with.
So should everyone spend more than 4%? Of course not.
If you retire at 50 and need your money to last 50 years, you should probably be more conservative. If you retire at 70, you can likely spend more. Your investment allocation matters too. Holding everything in cash and bonds isn’t necessarily “safer.” You need enough equity exposure to grow your portfolio and keep up with inflation over a long retirement.
But, I think the most important problem with the rule is that it ignores flexibility. If the market crashes 30%, you keep increasing your spending with inflation. If the market goes up 30%, you do the same thing.
Does anyone actually live like that? I doubt it. If my portfolio gets crushed during a recession, maybe I don’t take the expensive European vacation that year. If the market has an incredible five-year run and my portfolio doubles, maybe I spend a bit more.
This flexibility matters because one of the biggest risks in retirement is having terrible investment returns during your first few years. If you’re withdrawing money while your portfolio is down significantly, you’re selling assets at the worst possible time and leaving less capital available for the eventual recovery.
This is why I like thinking about the 4% rule as a starting point. Your real withdrawal rate should depend on your age, investments, spending needs, and most importantly, your willingness to adjust.
Response Times: I reached out to three estate attorneys last week to see if they could help a client of mine. Five days later, I've only heard back from one.
Maybe they’re on vacation. Maybe they’re slammed with work. But, it still amazes me that they didn't even acknowledge the email. I'm trying to give them work!
Unfortunately (or fortunately), we live in a world where speed matters. This is especially true in professional services. When someone reaches out to you, they’re trusting you with a problem. Responding quickly shows them that you’re organized, reliable, and on top of things.
I’ve always try to respond to emails quickly. That doesn’t mean I always have the answer. But there’s a big difference between having the answer and acknowledging the question. Oftentimes I'll just say “got it. Let me look into this and I’ll get back to you tomorrow.”
That takes 15 seconds and completely changes the experience for the person on the other side.
But, I still struggle with this. As someone who wants to manage my personal life, there’s an obvious downside to this mentality.
If you feel obligated to respond to every email immediately, you’re never really off. You’re checking your phone at dinner. You’re responding on vacation. You’re interrupting focused work because an email popped into your inbox. Being responsive can turn into allowing everyone else to control your time.
Philosophically, I don’t think the answer is responding to everything within 5 minutes. That’s probably not healthy or necessary. But, I do think there’s a reasonable middle ground. During the work week, acknowledge people quickly. Set expectations when you need more time. And when you’re actually off, be off.
The more interesting debate is whether I can have an AI agent handle and triage emails when I want to be off. For example, certain emails can be automatically acknowledged and added to my to-do-list for the next day. Urgent emails can be texted to me so I can handle manually right away. Has anyone set this up for themselves?
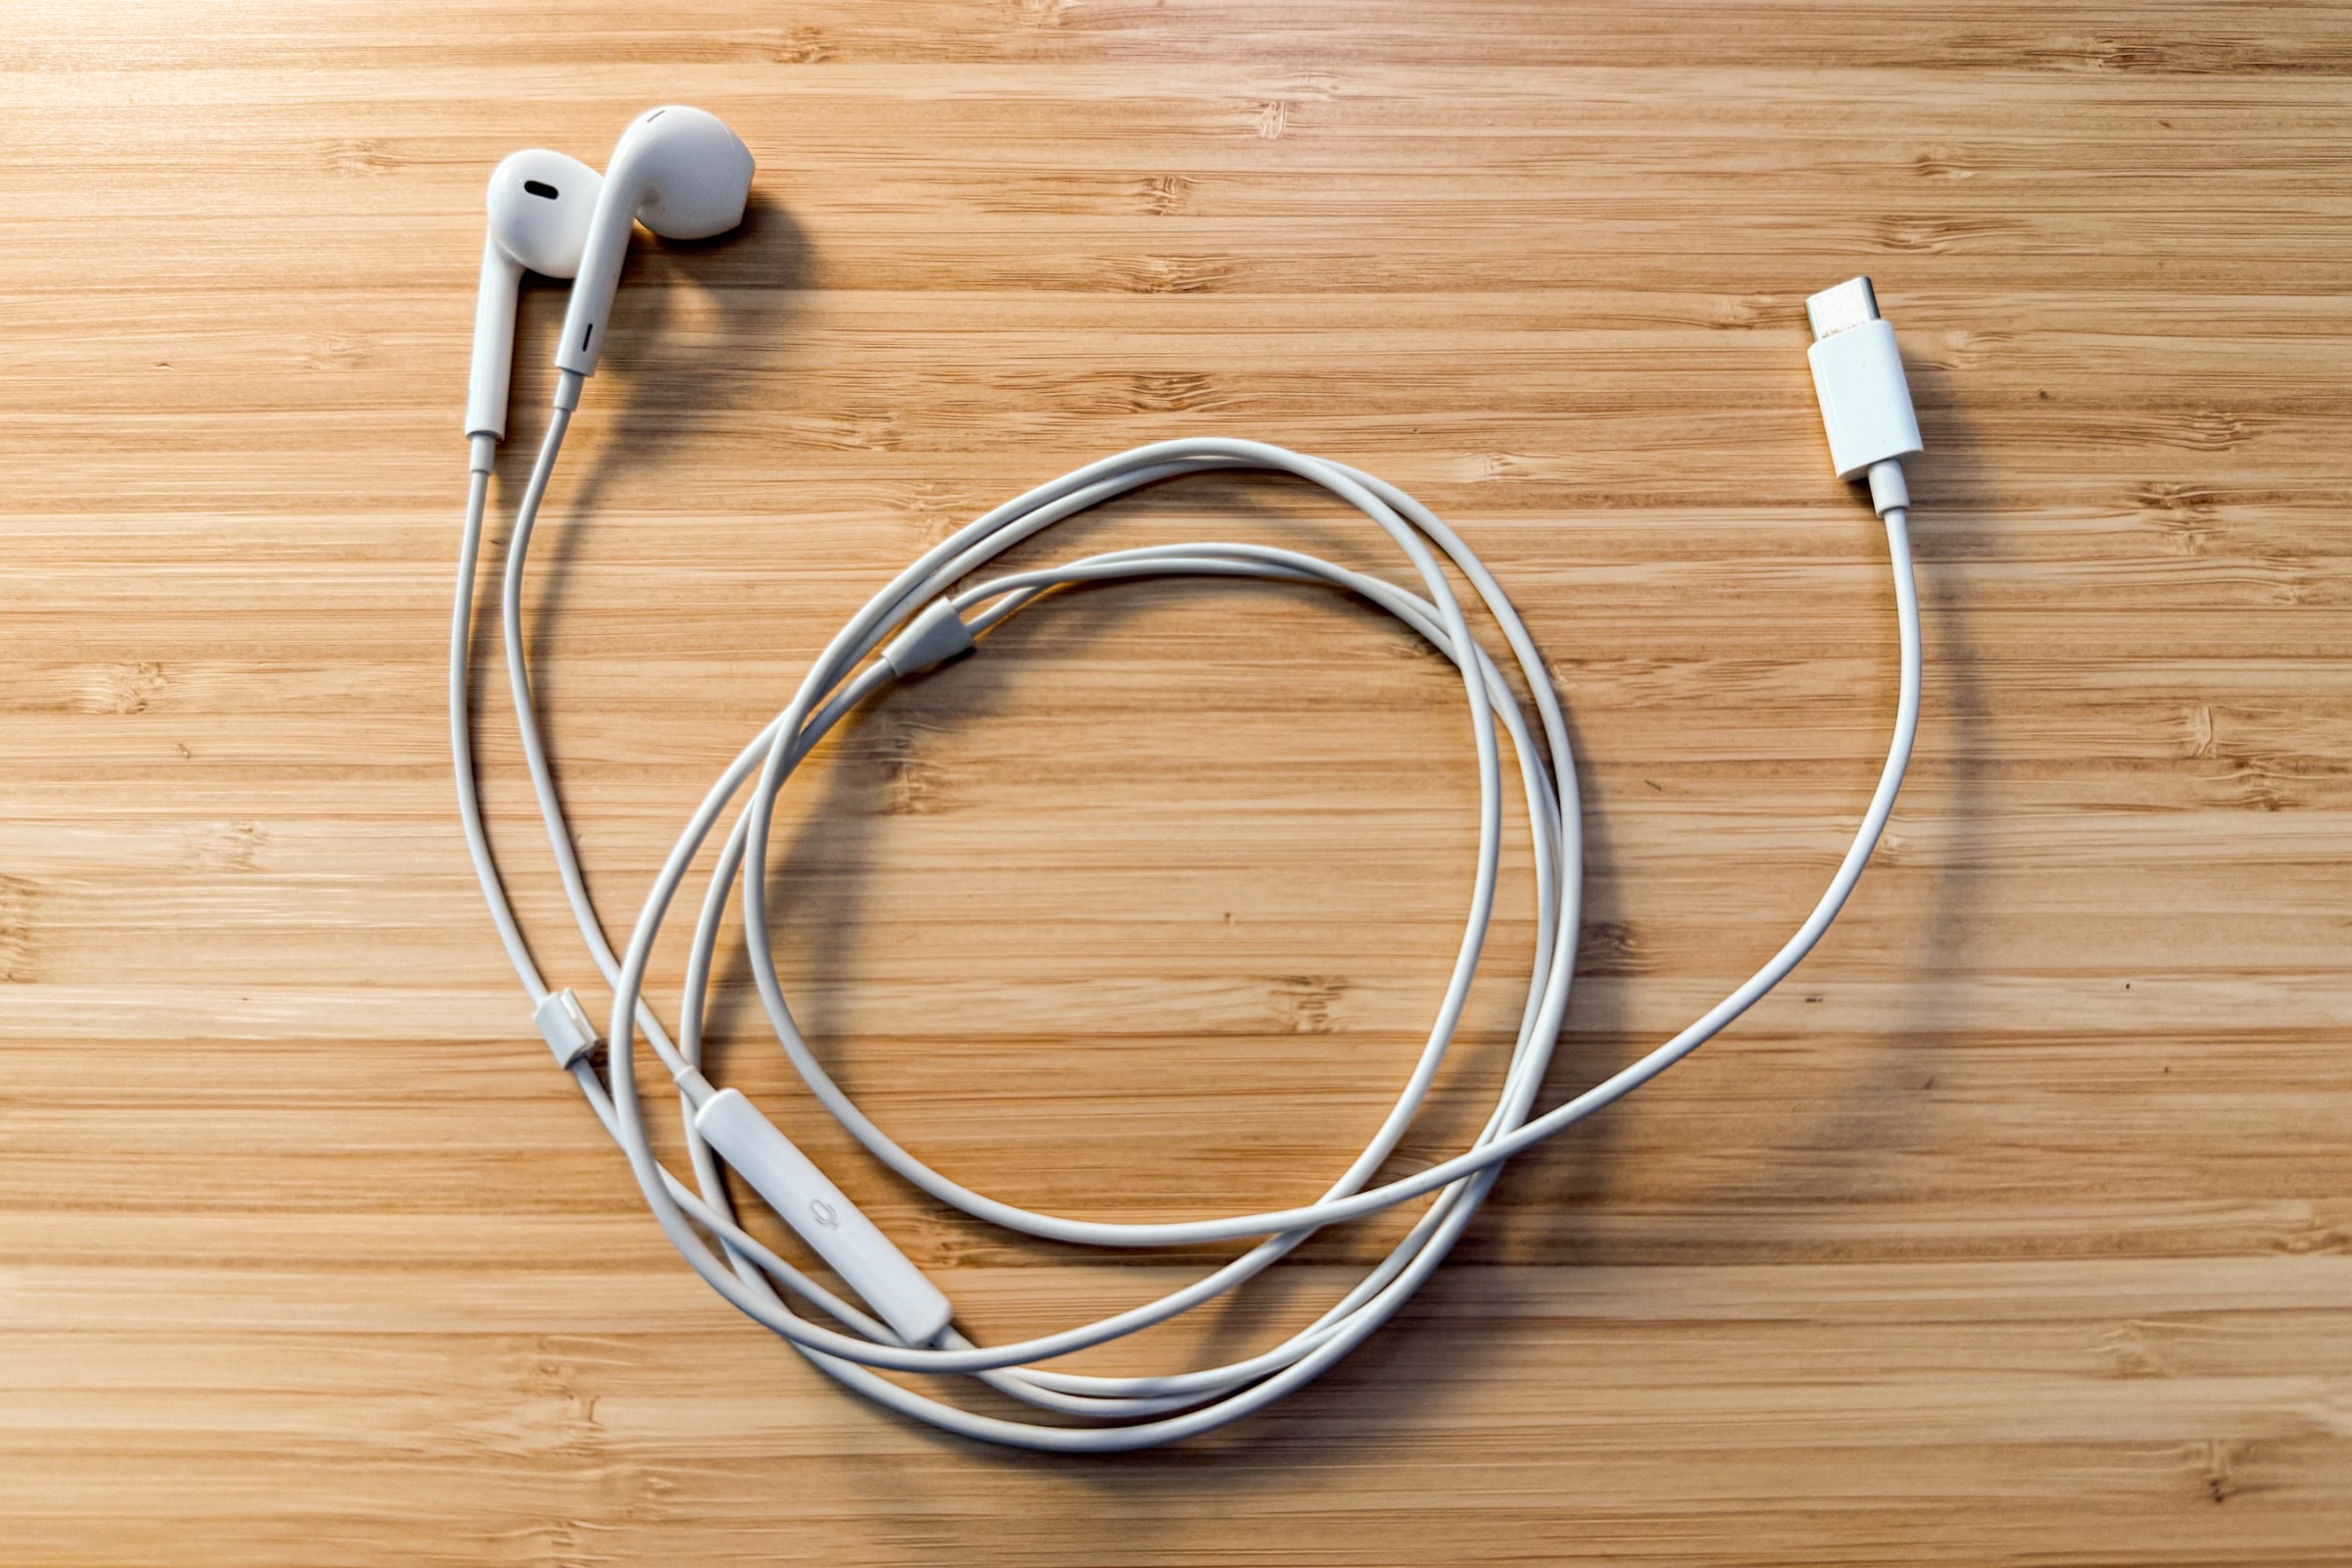
Wired Earpods: I may or may not have talked about this in the past, but I'm pretty reliant on my Bose over the ear headphones. I wear them almost my entire work day (which can't be good for me), but I'm fed up with bluetooth issues. Someone calls my phone and my headphones go nuts, sometimes my battery dies and sometimes they just don't work. Frustrating.
So, I've been using the apple wired headphones for the last year or so anytime I'm on a call. It's amazing. They always work. There's no fussing needed. No, they're not quite as comfortable so every time I get lazy and decide to keep on my Bose headphones for a call, something goes wrong.
So, staying strong with my wired headphones!
Disclaimer: VDB Wealth is a registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Investments involve risk and unless otherwise stated, are not guaranteed. Past performance is not indicative of future performance.
Unsubscribe | Update your profile | 412 N Main Street, Suite 100, Buffalo, WY 82834

We work with a select group of clients to provide tailored, high-touch wealth management. Ready to see how we can help?
Our personalized process ensures you receive expert financial guidance tailored to your unique goals. Get in touch in the way that works best for you—fill out the contact form, send us an email, or schedule a call. However you choose to reach out, we’re here to help you build, grow, and protect your wealth.
VDB Wealth LLC is a registered investment adviser located in the State of Georgia. Registration as an investment adviser does not imply a certain level of skill or training.
The information on this website is for informational purposes only and does not constitute investment, legal, tax, or financial advice. Nothing on this site should be interpreted as a solicitation, offer, or recommendation to buy or sell any securities or investment products. All investments involve risks, including the potential loss of principal.
VDB Wealth LLC provides investment advisory services only to residents of states where it is properly registered or exempt from registration. Past performance is not a guarantee of future results.
VDB Wealth LLC | (415) 209-5862 | contact@vdbwealth.com