
As I build my boutique wealth management firm, I'm looking to partner with the right people and families. If you've ever wondered whether it might be a fit, or you just want a second opinion on your current setup, feel free to reach out. Always happy to talk.
Just reply to this email.
Bond Yields: For the first time in a long time, boring bonds are starting to look pretty sexy. The 30-year US Treasury is currently yielding around 5.3%. The 10-year is yielding around 4.8%.
But, you may be wondering why rates are going up in the first place.
There’s never one simple answer, but investors seem increasingly concerned about a combination of persistent inflation, massive government borrowing, and an economy that continues to demand a lot of capital. The US government needs to borrow a lot of money. At the same time, companies are spending enormous amounts on AI infrastructure and data centers. More borrowers are competing for capital, and lenders are demanding higher returns to provide it.
I know a lot of people looking at a 30-year yields over 5% and getting pretty excited. You can give the US government $1m and collect more than $50k per year for the next 30 years. Assuming the US government pays its debts, you know exactly what you’re going to get.
Sounds pretty damn good. There’s just one problem. Inflation.
If inflation averages 3% over the next 30 years, your actual return is only around 2% per year. Even worse, you’re making a 30-year bet on what inflation will look like. If inflation ends up meaningfully higher than expected, that 5% becomes a lot less attractive.
This is where TIPS get interesting. TIPS are Treasury Inflation-Protected Securities. Instead of locking in a fixed nominal return, the principal value adjusts with inflation. You’re effectively locking in a return above inflation.
As of this week, the 30-year TIPS yield is around 3%.
If you buy a 30-year TIPS and hold it to maturity, you’re effectively locking in roughly a 3% annual return above measured inflation before taxes. If inflation averages 2%, your return will be roughly 5%. If inflation averages 4%, it’ll be roughly 7%.
Does this mean everyone should go buy TIPS? Absolutely not.
There are plenty of reasons you may prefer traditional Treasuries, equities, cash, or other investments. TIPS also have their own complexities around taxes, liquidity, and price volatility if you need to sell before maturity.
As with everything, the most important question is what you’re trying to accomplish with your money. If you’re trying to maximize long-term wealth, owning equities may still make far more sense. If you’re trying to protect purchasing power and reduce risk, today’s bond market suddenly gives you some options.
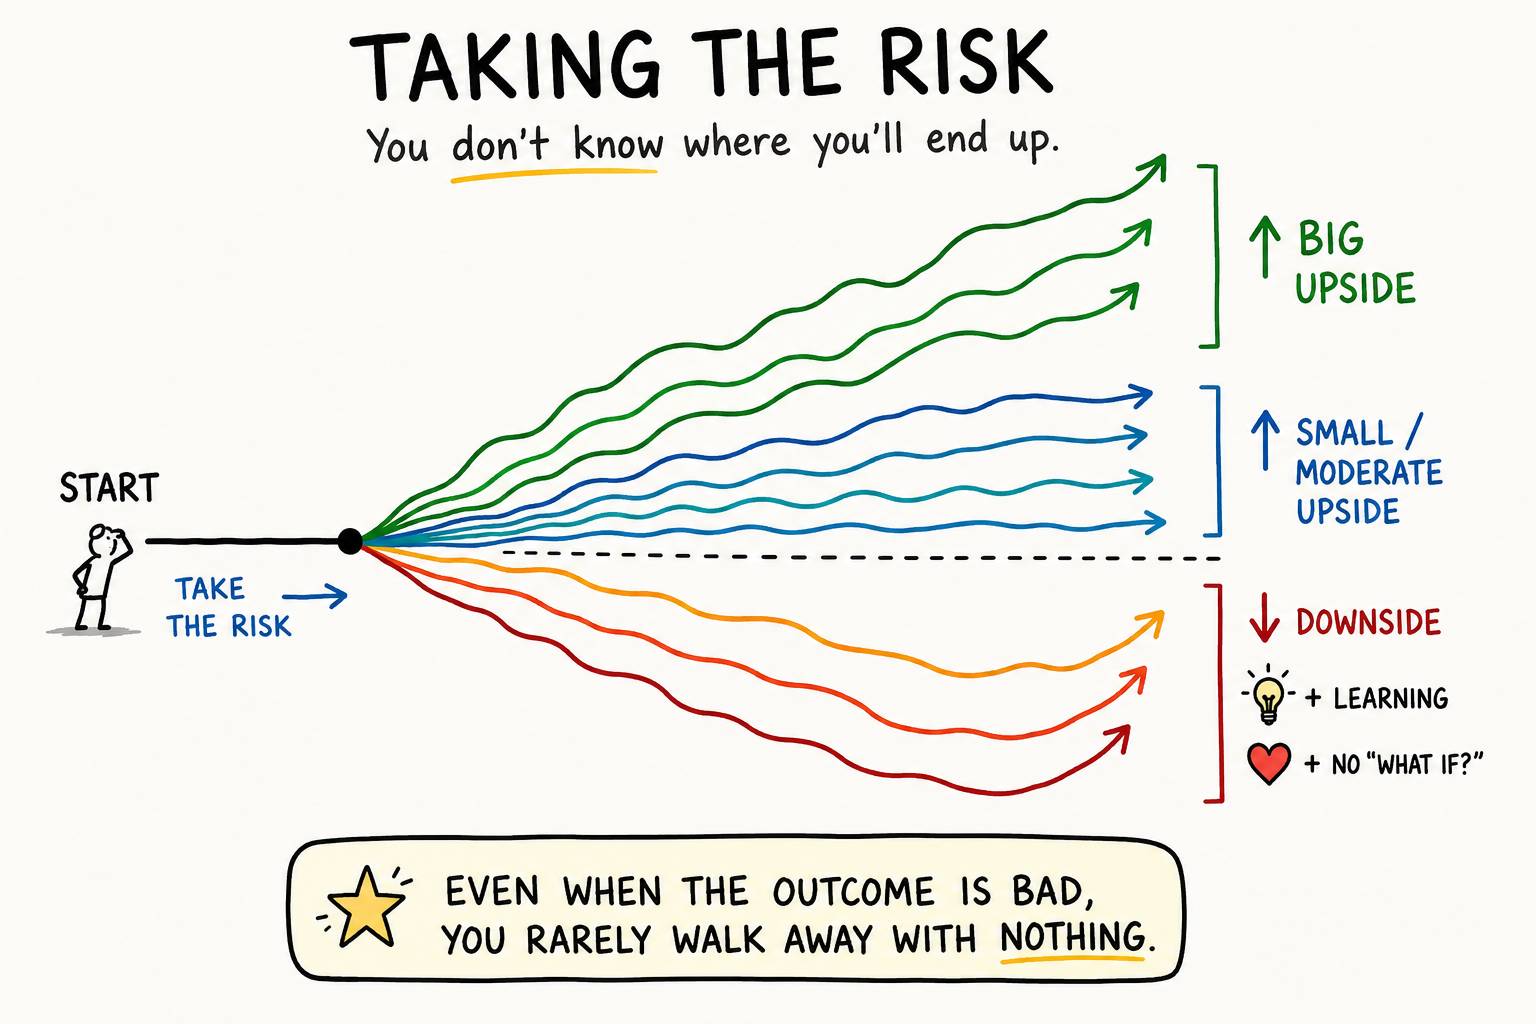
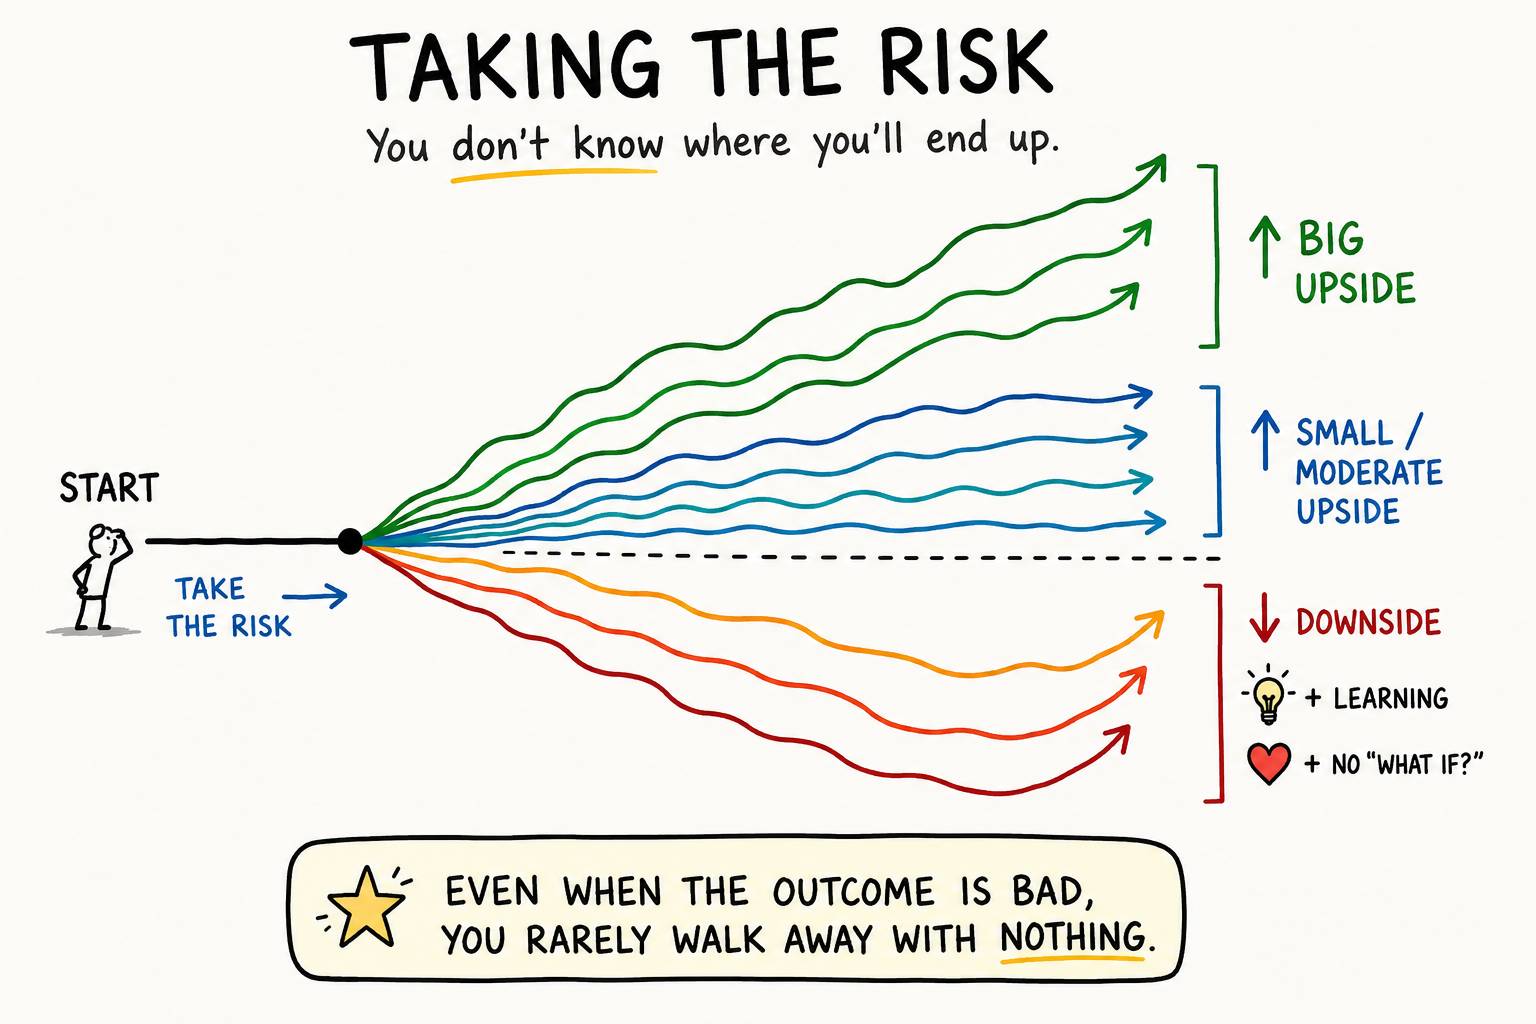
Taking the Risk: I’ve always considered myself a conservative entrepreneur. I like starting businesses, but I tend to play it "safe." I like trying new things, but I spend way too much time thinking about what could go wrong. I want to think bigger, but my natural instinct is to protect the downside.
When you take a risk, there are three potential outcomes:
But even in that last scenario, you rarely walk away with nothing.
You learn something. You meet people. You get better at making decisions. You eliminate one of those annoying “what if?” questions that can sit in the back of your head for years. You do more interesting things.
When I look back at my own life, some of my best decisions started with a pretty uncomfortable amount of uncertainty.
The upside of taking a risk can be enormous. The downside is often capped. And even when you experience the downside, you usually get something back.
Obviously, this doesn’t mean you should make reckless decisions. You should probably build a spreadsheet and model every possible downside before doing anything meaningful.
But I’m advocating we place less emphasis on “What happens if this doesn’t work?” and more on “If this doesn’t work, what will I still walk away with?”
And if the upside could meaningfully change your life?
Maybe you should take the risk.
Something New Substack: I've made great friends via the internet and I feel lucky to know Tess and Buckley. Not only are they residents of the South, they spend summers in Northern Michigan. I won't go into too much detail, but they've had a really hard year. Despite the challenges, Tess decided to start writing again and it's impressive. You can immediately tell when someone has a gift and despite my liberal arts education, I lack the talent that she possess.
If you enjoy good writing and various life thoughts, I'd encourage you to read her piece here. I promise it will make you want to sign-up.
Disclaimer: VDB Wealth is a registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Investments involve risk and unless otherwise stated, are not guaranteed. Past performance is not indicative of future performance.

We work with a select group of clients to provide tailored, high-touch wealth management. Ready to see how we can help?
Our personalized process ensures you receive expert financial guidance tailored to your unique goals. Get in touch in the way that works best for you—fill out the contact form, send us an email, or schedule a call. However you choose to reach out, we’re here to help you build, grow, and protect your wealth.
VDB Wealth LLC is a registered investment adviser located in the State of Georgia. Registration as an investment adviser does not imply a certain level of skill or training.
The information on this website is for informational purposes only and does not constitute investment, legal, tax, or financial advice. Nothing on this site should be interpreted as a solicitation, offer, or recommendation to buy or sell any securities or investment products. All investments involve risks, including the potential loss of principal.
VDB Wealth LLC provides investment advisory services only to residents of states where it is properly registered or exempt from registration. Past performance is not a guarantee of future results.
VDB Wealth LLC | (415) 209-5862 | contact@vdbwealth.com